Cromwell European REIT (“CEREIT”) is looking to diversify its funding sources by tapping the SGD bond market. The company has announced a perpetual note offering with an initial price guidance (“IPG”) of 5.125%. The notes are first callable in November 2026.
About the perpetual notes
Priced under the terms of its recently established SGD 750m Multicurrency Perpetual Securities Programme (the “Programme”), the perpetual notes are unsecured and subordinated securities of the issuer. The notes have a first call date in November 2026. If not redeemed on its first call date, the distribution rate on the perps will reset to the prevailing 5-year SORA-OIS rate + initial spread. Outstanding notes are callable thereafter on every distribution date.
In addition, the perps may be redeemed at 100 for tax or accounting reasons as defined in the Programme. In other circumstances, the perps are also redeemable if there are any changes to the Property Funds Appendix (i.e. Appendix 6 of the Code on Collective Investment Schemes issued by the Monetary Authority of Singapore), such that the perpetual notes count towards the calculation of Aggregate Leverage as defined under the Property Funds Appendix. Other redemption events include Tax Deductibility situations, Ratings or even Minimal Outstanding Amount events.
The issuer may elect to defer distribution payments. Any deferred distributions are non-cumulative and non-compounding. A dividend stopper clause is also applicable.
The use of proceeds from the issuance of the perpetual securities will be used for financing or refinancing of its acquisitions and/or investments. CEREIT may also use the proceeds to refinance its existing borrowings and general corporate purposes.
About CEREIT
Cromwell European Real Estate Investment Trust is Singapore’s first publicly listed REIT with a European portfolio managed by Cromwell EREIT Management Pte. Ltd. (the “CEREIT Manager”). Cromwell EREIT Management Pte. Ltd. is a wholly owned subsidiary of Cromwell Property Group. Cromwell Property Group is the sponsor of CEREIT.
CEREIT has 109 properties in the portfolio with EUR 2,347.3m of office and logistics assets located in major European cities. CEREIT was constituted between the CEREIT Manager and Perpetual (Asia) Limited (the “CEREIT Trustee”) by a Trust Deed dated 28 April 2017. The REIT is rated ‘BBB-‘ by Fitch Ratings with a stable outlook.
About the sponsor
Cromwell Property Group, the sponsor of CEREIT, is a 28.03% unitholder of CEREIT as at 30 June 2021. Listed on the Australian Stock Exchange, the sponsor is a global real estate investor and manager with AUD 11.9b of assets under management as at June 2021. Close to 50% of the assets are in Europe while 42.4% are in Europe and 8.2% in New Zealand. A majority of the properties are offices (66.0%), followed by retail (13.6%) and industrial/logistics (6.1%) properties.
About the issuer
Cromwell European REIT is reorganising the group in a manner that will result in Cromwell EREIT Lux 2 S.à r.l. becoming the parent company of the operating subsidiaries (see Figure 1). All of the European entities of CEREIT will be under Cromwell EREIT Lux 2 S.à r.l.
CEREIT and the holding companies in Singapore will have no material assets apart from the shares of Cromwell EREIT Lux 2 S.à r.l., as well as the shareholder debt owed by Cromwell EREIT Lux 2 S.à r.l.
Figure 1: Proposed group structure post reorganisation
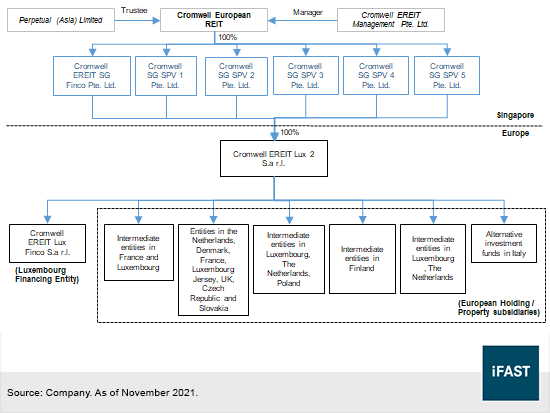
Perpetual (Asia) Limited, the trustee of Cromwell European Real Estate Investment Trust, is the issuer of the new perpetual notes. The issuer depends on the payments and distributions from its operating subsidiaries for income and cash flows. The REIT’s properties are held directly or indirectly by the operating subsidiaries, which are in turn held directly or indirectly by the issuer through various Singapore and European holding companies (see Figure 1).
The CEREIT Manager is able to direct the trustee to borrow or raise money for the purposes of CEREIT, both on a secured and unsecured basis.
Perpetual (Asia) Limited is incorporated in Singapore with a paid-up capital of SGD 9,024,811 as at 22 October 2021. It is an indirect wholly-owned subsidiary of Perpetual Limited, a listed company on the ASX and one of the largest independent trustees in Australia. Perpetual (Asia) Limited is licensed as a trust company under the Trust Companies Act of Singapore. It is regulated by MAS and approved to act as a trustee for authorised collective investment schemes.
As a CEREIT trustee, any liability incurred and any given indemnity shall be limited to the assets of CEREIT over which the trustee has recourse, on condition that that the trustee has acted without fraud, gross negligence, wilful default or breach of the Trust Deed. There are certain indemnities in favour of the Trustee mentioned in the Trust Deed under which it will be indemnified out of the CEREIT assets for liabilities arising from certain acts.
Under condition 14.7 of the memorandum, the issuer is able to replace Perpetual (Asia) Limited as the Principal Debtor under the notes and the Trust Deed subject to the fulfilment of certain terms.
Portfolio properties
CEREIT had a portfolio weighted average lease expiry (“WALE”) of 4.7 years and a weighted average lease to break (“WALB”) of 3.2 years in September 2021. This was down slightly from September last year (WALE: 5.0 years; WALB: 3.4 years). Portfolio occupancy however rose to 95.3% in September 2021 from 94.3% a year ago. Most of its properties are in the Netherlands as they made up 27.2% of the portfolio by valuation.
Italy is also a large credit determinant as it contributed the most Net Property Income (“NPI”) during the 9 month period ended 30 September 2021 (“9M21”). Italy grew its GDP by 2.6% during the September quarter and this was above the European average (of +2.2%). The country has one of the highest proportion of vaccinated people and economic activity is returning to normal.
Most than half (56.0%) of the portfolio’s valuation is represented by office properties, which contributed 54.7% of the REIT’s 9M21 NPI. As seen in Table 1, office occupancies have dropped from 94.3% in 2Q21 to 93.2% in 3Q21. In particular, occupancies in Poland and Finland fell to 88.5% and 81.8% respectively. Overall, the manager reported that many tenants are renewing or extending leases but new leases are completing on less space than previously planned.
Table 1: Property portfolio overview as of 3Q21
|
Asset type |
Location |
NLA (sqm) |
Valuation (EUR m) |
Occupancy (3Q21) |
Occupancy (2Q21) |
9M21 NPI (EUR m) |
|
Office |
The Netherlands |
177,902 |
572.3 |
97.5% |
97.3% |
19.5 |
|
Industrial / Logistics |
The Netherlands |
46,292 |
67.5 |
100.0% |
100.0% |
2.5 |
|
Office |
Italy |
142,177 |
324.0 |
98.5% |
98.5% |
12.8 |
|
Industrial / Logistics |
Italy |
186,526 |
67.9 |
99.6% |
99.7% |
3.3 |
|
Others |
Italy |
176,575 |
125.9 |
100.0% |
100.0% |
7.5 |
|
Office |
France |
34,320 |
70.1 |
85.6% |
84.2% |
4.4 |
|
Industrial / Logistics |
France |
248,076 |
343.7 |
93.5% |
92.6% |
14.9 |
|
Industrial / Logistics |
Germany |
226,985 |
207.3 |
96.2% |
95.6% |
7.9 |
|
Office |
Poland |
111,241 |
235.8 |
88.5% |
93.5% |
12.1 |
|
Office |
Finland |
61,949 |
111.8 |
81.8% |
82.8% |
4.5 |
|
Industrial / Logistics |
Denmark |
129,817 |
84.8 |
86.9% |
80.0% |
4.0 |
|
Industrial / Logistics |
The Czech Republic |
59,499 |
61.1 |
99.6% |
99.6% |
1.7 |
|
Industrial / Logistics |
Slovakia |
74,355 |
63.4 |
100.0% |
99.6% |
2.2 |
|
Industrial / Logistics |
United Kingdom |
9,764 |
11.6 |
100.0% |
N.A. |
0.1 |
|
Office |
All |
527,589 |
1,314.0 |
93.2 |
94.3 |
53.3 |
|
Industrial / Logistics |
All |
981,314 |
907.3 |
95.6 |
94.3 |
36.6 |
|
Others |
All |
176,575 |
125.9 |
100.0 |
100.0 |
7.5 |
|
All |
All |
1,685,478 |
2,347.3 |
95.3% |
94.9% |
97.4 |
| Source: Company, As of 3Q21 | ||||||
3Q21 portfolio performance highlights
CEREIT recorded EUR 50.7m of gross revenue in 3Q21, up from EUR 46.1m in 3Q20. NPI increased to EUR 33.2m during the quarter (3Q20: EUR 30.6m), driven by strong leasing activity in the light industrial/logistics portfolio in Denmark, offset by weakness in the Poland. Net income after tax and before fair value changes rose slightly from EUR 21.7m in 3Q20 to EUR 23.6m in 3Q21.
Underpinning the revenue growth are positive rental reversions with rent reversions of +1.2% in 3Q21 (2Q21: +10.0) and +4.3% in 9M21. CEREIT reported 29 new leases and 18 renewals during 3Q21, and 38 new leases and 17 renewals in 2Q21.
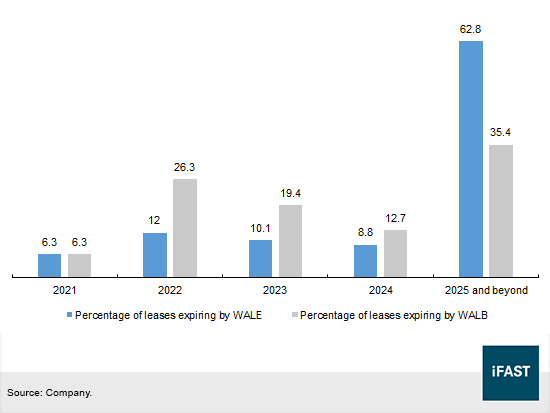
One of the glaring downsides is that 26.3% of leases by breaks, whereby tenants have the option to pre-terminate leases, are occurring in 2022 (Figure 2). However, management guided that 41.8% of breaks and expiries until 31 March 2022 have been de-risked.
Figure 2: Percentage of leases expiring / breaking by year
Average vacancy rates in the European office sector have increased from 8.3% in 1Q21 to 8.6% in 2Q21, as more tenants are reassessing their space requirements. Office occupancies have turned lower in 3Q21 and may weigh on the portfolio’s performance.
The REIT is aware of the weakness in office space demand and has been increasing its exposure to logistics properties. CEREIT is pivoting towards a 50% portfolio weighting to the light industrial and logistics sector. In August 2021, CEREIT acquired a freehold logistics asset in the UK for GBP 10.0m (~EUR 11.7m). Earlier this month on 1 November 2021, the trust announced a EUR 19.6m acquisition in an Italian industrial asset with a potential Net Operating Income yield of 6.5%.
Credit discussion
CEREIT has a healthy credit profile, with an interest coverage ratio of 5.8x as at 30 September 2021 (measured on a trailing 12-month basis in accordance with the Property Funds Appendix). Aggregate Leverage, defined as the proportion of debt to deposited property value is adequate at 37.8%.
To put these numbers in perspective, Suntec REIT (which is a Singapore office REIT) has an adjusted interest coverage ratio of 2.7x and an Aggregate Leverage ratio of 44.3%. With a total debt outstanding amount of SGD 5,155m and a 3Q21 NPI of SGD 68.8m, Suntec REIT is a much larger trust with a moderately higher debt burden than CEREIT.
Financial covenants under certain borrowings require CEREIT to maintain a consolidated leverage (or gearing) ratio below 45%, a debt yield (Adjusted consolidated profits before interest and tax to consolidated net borrowings) of at least 0.11 to 1, a priority debt ratio of 30% or lower, and an unencumbrance ratio of 220%.
None of the covenants were breached as at 30 June 2021. CEREIT reported that consolidated leverage ratio was 37.9%, the debt yield was at 0.142 to 1, the priority debt ratio at 3.4% (3Q21: 3.4%) and the unencumbrance ratio at 260% (3Q21: 247.7%).
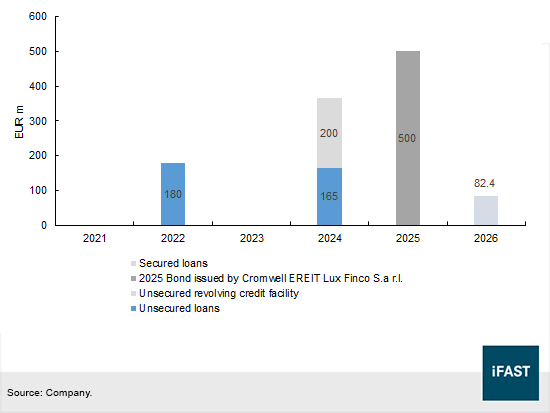
Last year, the trust refinanced a number of its debt and managed to extend the maturities of its borrowings. Its debt maturity profile in Figure 3 shows that the trust has ample liquidity. It does not have any debt maturing until November 2022. In their last unaudited financial statement, CEREIT recorded EUR 80.7m of cash and cash equivalents with no current borrowings in 1H21.
Figure 3: Pro-forma debt maturity profile
Relative valuation
Cromwell European Real Estate Investment Trust is pricing its new SGD NC5 perpetual notes at an initial price guidance of 5.125%. The 5.125% price guidance is 374.3 basis points higher than the 5-year SORA-OIS on 17 November 2021. As reference, the CERTSP 2.125% 19Nov2025 Corp (EUR) – issued by Cromwell EREIT Lux Finco S.à r.l. - has a G-spread of 178 basis points which is measured in EUR terms. We think that the initial price guidance of 5.125% is fairly priced, and likely reflective of the trust’s small asset base and niche focus in Europe.
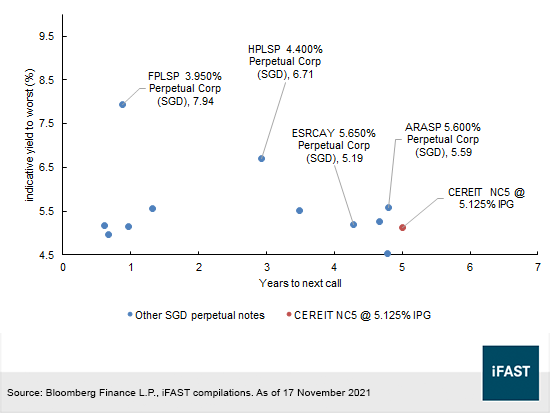
Looking at other SGD perpetual notes within the space (see Figure 4), the ESRCAY 5.650% Perpetual Corp (SGD) and ARASP 5.600% Perpetual Corp (SGD) have slightly higher yields with shorter call dates, and would be more attractive compared to the new CEREIT NC5 perps. ESR Cayman and ARA Asset Management are larger property managers. The former is in the midst of acquiring ARA Asset Management to become the world’s third largest listed real estate asset manager.
However, the new CEREIT NC5 notes are more attractive compared to the Suntec REIT perps. SUNSP 3.800% Perpetual Corp (SGD) and SUNSP 4.250% Perpetual Corp (SGD) have lower yields and are trading at an indicative yield-to-worst (“YTW”) of 3.99% and 4.16% respectively.
Figure 4: Relative valuation among SGD perpetual bonds
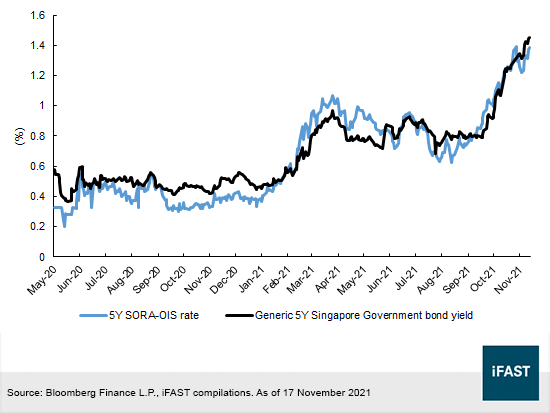
On a side note, 5-year benchmark yields have been increasing and could place pressure on bond prices in the short term. As seen in Figure 5, 5-year Singapore Government bonds now trade at a yield of 1.4490%, up from 0.4560% at the start of the year. 5-year SORA-OIS rates have also increased. Some of the recently issued bonds have fallen below par due to rate pressures. With this in mind, we think that the new CEREIT NC5 notes would be attractively priced if they were priced above the ARASP 5.600% Perpetual Corp (SGD) (i.e. as if they were the highest yielding note along the 5-year mark). It will make a worthwhile consideration if the price guidance was more than 5.59% but at the current IPG it’s fairly priced.
Figure 5: 5-year SGD benchmark rates
Declaration: For specific disclosure, at the time of publication of this report, IFPL (via its connected and associated entities) holds a position in ARASP 5.200% Perpetual Corp (SGD), ESRCAY 5.65% Perp Corp (SGD), ESRCAY 6.750% 01Feb2022 Corp (SGD), FPLSP 4.980% Perpetual Corp (SGD), SUNSP 3.800% Perpetual Corp (SGD) and ESRCAY 7.875% 04Apr2022 Corp (USD). The analyst who produced this report holds a NIL position in the abovementioned securities.
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!